


Markit Recap – 8/3/2015

Spain is often held up as an example of how austerity works, and Markit data published on August 5 provides some support to this view. Markit PMIs for August showed that Spain was leading the way in the eurozone’s economic expansion. There are major questions over the country’s labour market – unemployment remains at stratospheric levels and most of the job creation is fuelled by low-paid, part-time work – but its recovery is nonetheless impressive compared with the rest of the southern Europe.
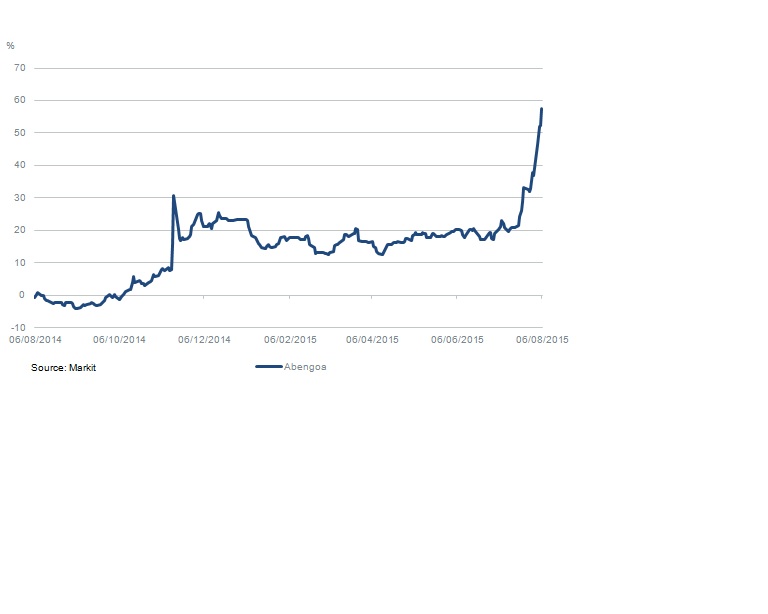
But Spanish credits aren’t really reaping the benefits. Most of the names trade in the CDS market have a global presence, and it is the exposure beyond Europe that is preventing material credit improvement. A prime example is Spanish energy firm Abengoa. The company announced a €650m cash call on August 3, apparently required to fund additional capital expenditure in Brazil. Abengoa’s private equity partner in Brazil has placed restrictions on its investments in Brazil, and the state-owned development bank BNDES recently introduced restrictions on leverage for power projects.
The company’s communication on these issues was questioned by investors, and to make matters worse it halved its free cash flow guidance for 2015 on July 31. Unsurprisingly, the reaction in the credit markets was negative. Abengoa was already trading at distressed levels, and the cash flow and capex bombshells caused its CDS levels to rocket from 37 points upfront to 52 points in the space of three days. It’s worth noting that Abengoa was added to the Markit iTraxx Crossover index last year, and has seen its trading liquidity improve significantly in the interim.
Abengoa is perhaps an extreme example of how Latin American exposure is damaging Spanish firms, but it certainly not the only credit affected. Spanish banks also have considerable exposure in the region, and the downturn in the Brazilian economy, in particular, will have detrimental effects. The slide in commodity prices has hit exports, and the persistent structural economic problems have added to negative sentiment.
Commodities have taken over from Greece as the main driver of market direction – at least for the time being – and investors will be closely watching CDS spreads of names with exposure, either directly or indirectly.
Contact: Gavan Nolan
Email: Gavan.Nolan@markit.com




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…