


Secondaries is a part of the private credit market that gained momentum last year and shows no signs of slowing.
This week has brought further evidence of the continuing rise of private credit secondaries, with French fund manager Eurazeo announcing a €480 million continuation vehicle backed by Pantheon.
Pantheon had already led a $3.2 billion Crescent Capital CV this year in what was the largest credit secondaries CV to date – moving past the $3 billion Coller Capital-led CV at TPG Twin Brook last summer.
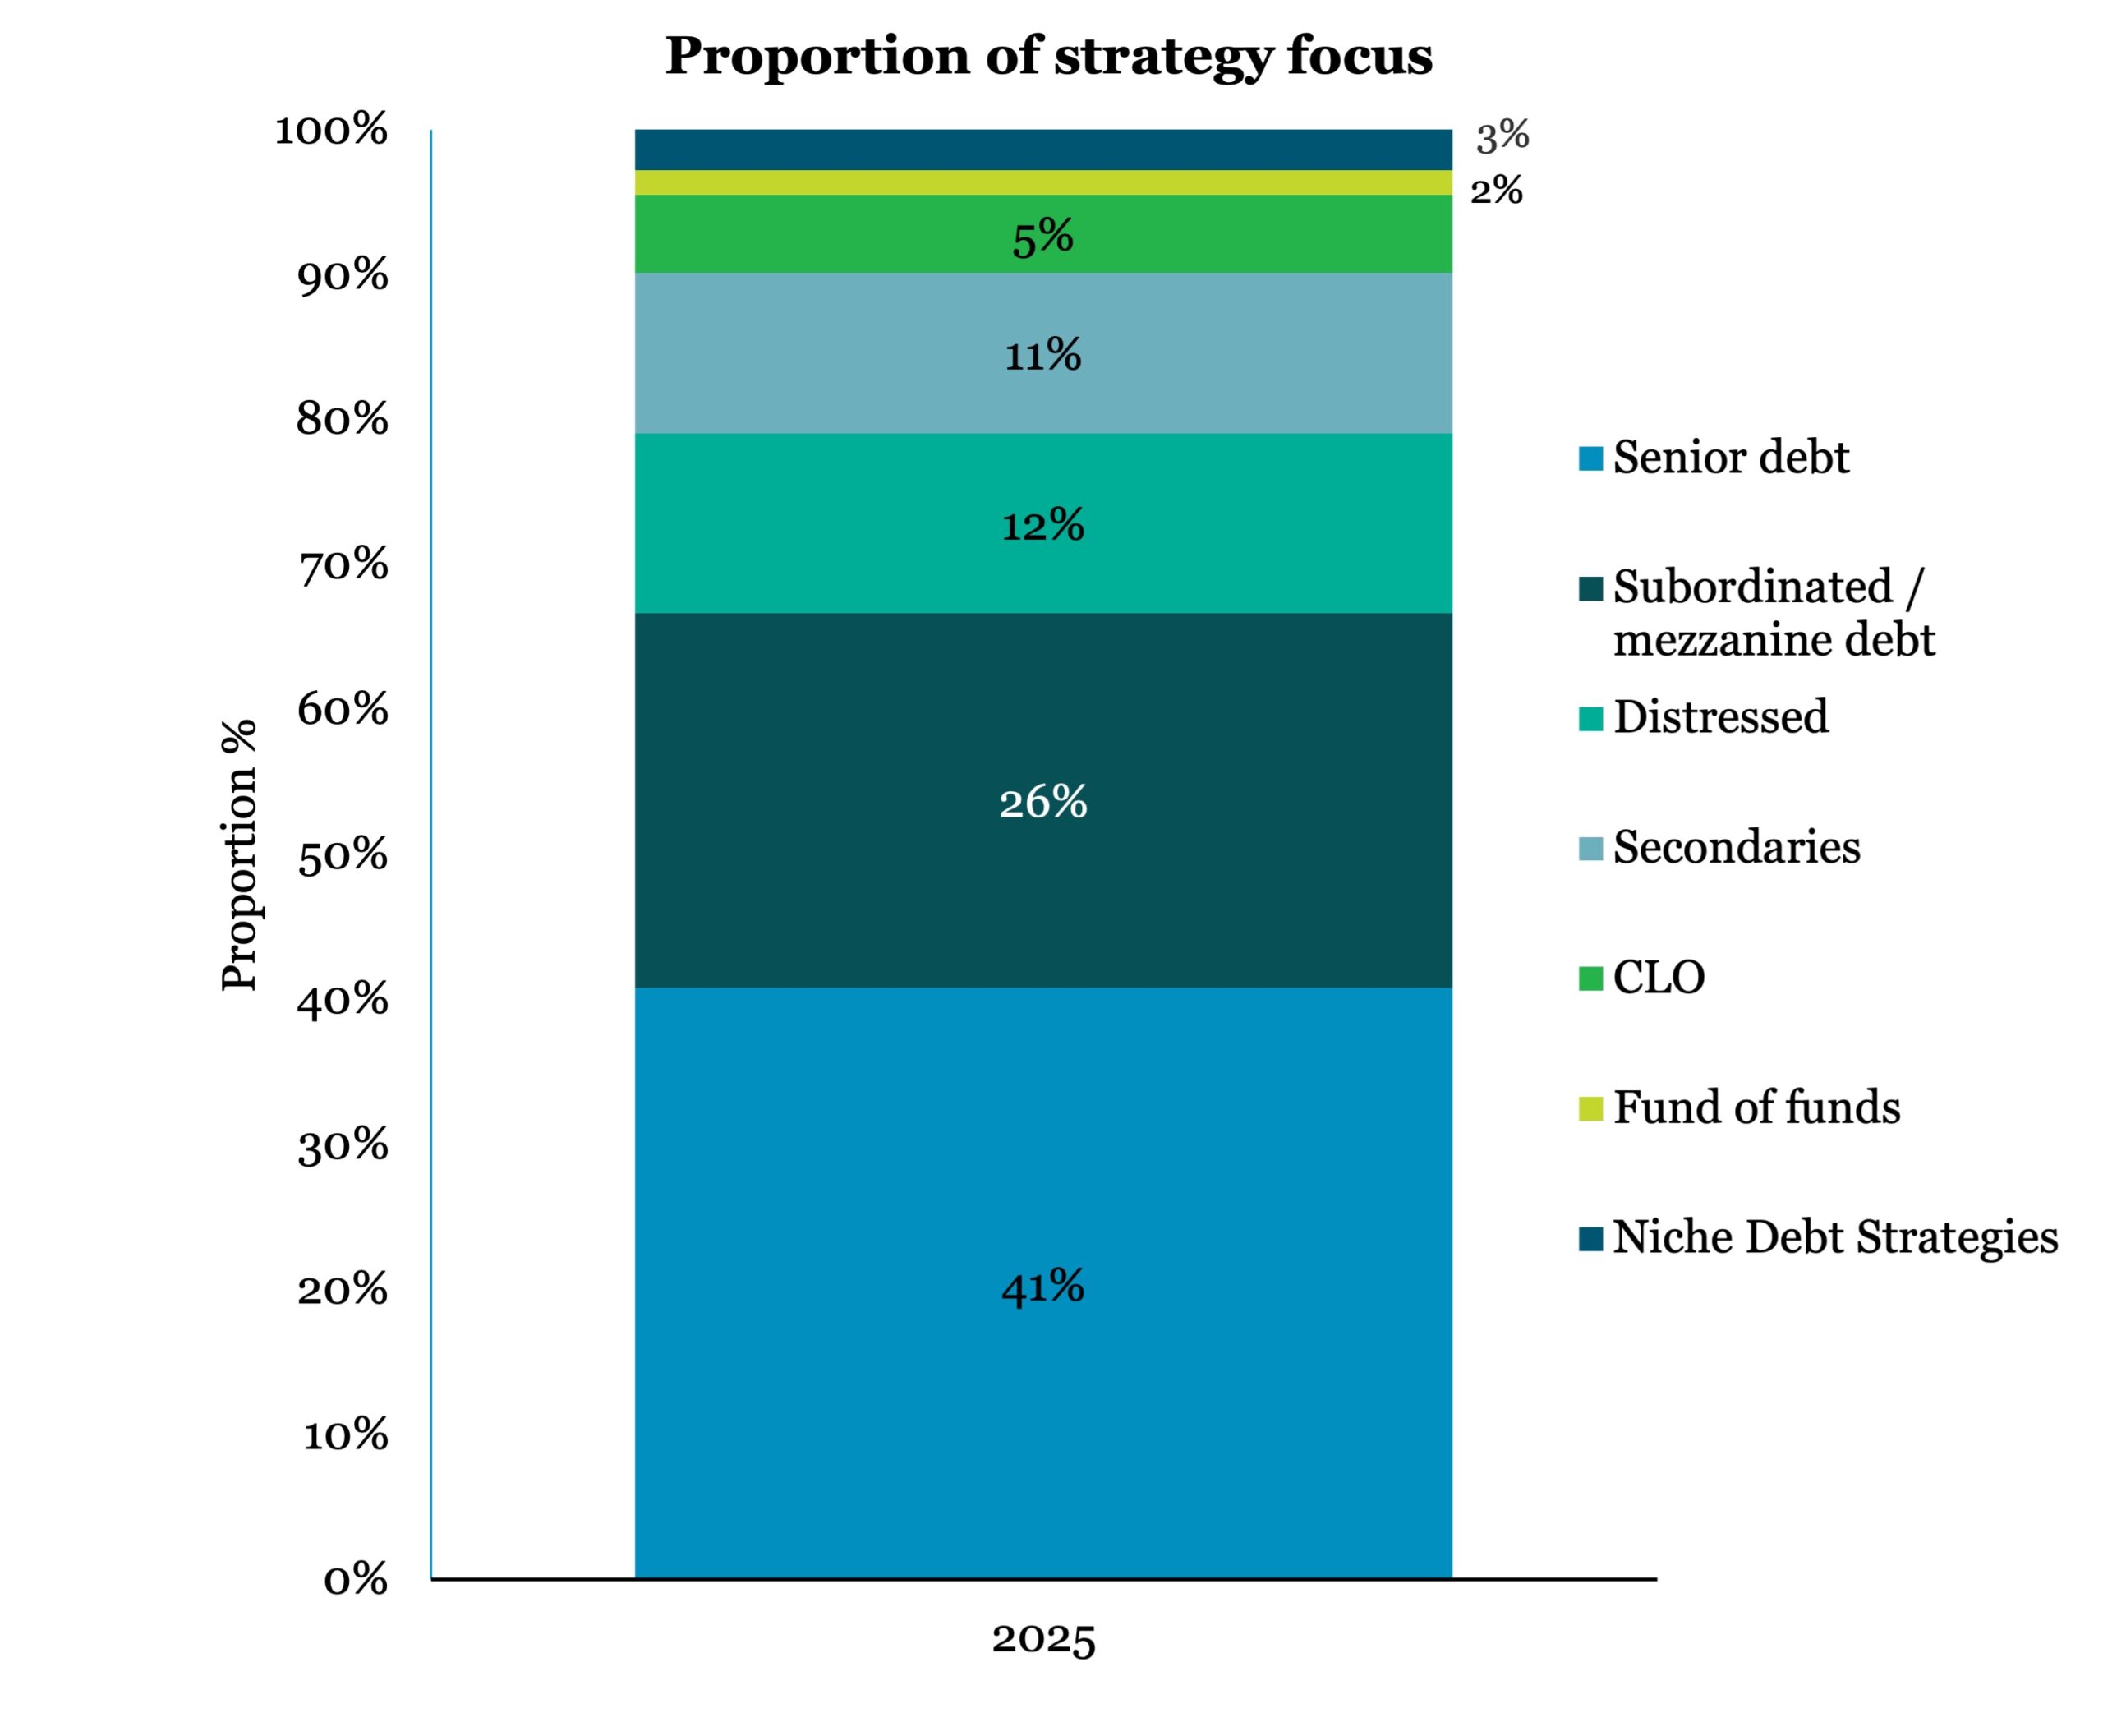
These deals are occurring against a backdrop of a prolific fundraising period for credit secondaries. Having accounted for no more than 3 percent of the global private credit fundraising total in previous years, that figure shot up to 11 percent last year (see chart).
If the early stages of 2026 are an accurate indicator, that proportion may very well increase further. In January, Ares Management announced it had raised over $7 billion for a credit secondaries strategy, including its largest ever inaugural institutional fundraise; while Coller Capital hauled in $17 billion across its secondaries strategies, of which credit is a part.
Growing LP appetite supports new players entering the booming credit secondaries market. About 38 percent of investors are actively investing into private credit secondaries this year, up from 34 percent in 2025, according to the latest Private Credit Market Report from placement agent and advisory firm Campbell Lutyens.
But despite the rapid growth of credit secondaries in recent years, volumes remain small relative to the private credit asset class as a whole. Private credit secondaries account for only around 0.25 percentage points of primary credit market volume, versus ratios closer to two percentage points in other asset classes, according to the Campbell report.
There is significant room for credit secondaries to scale further given strong investor appetite and the asset class’s still modest share of the primary market. With that backdrop, the emergence of even larger deals and fundraises in the year ahead looks inevitable.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
