
Download PitchBook’s Report here.
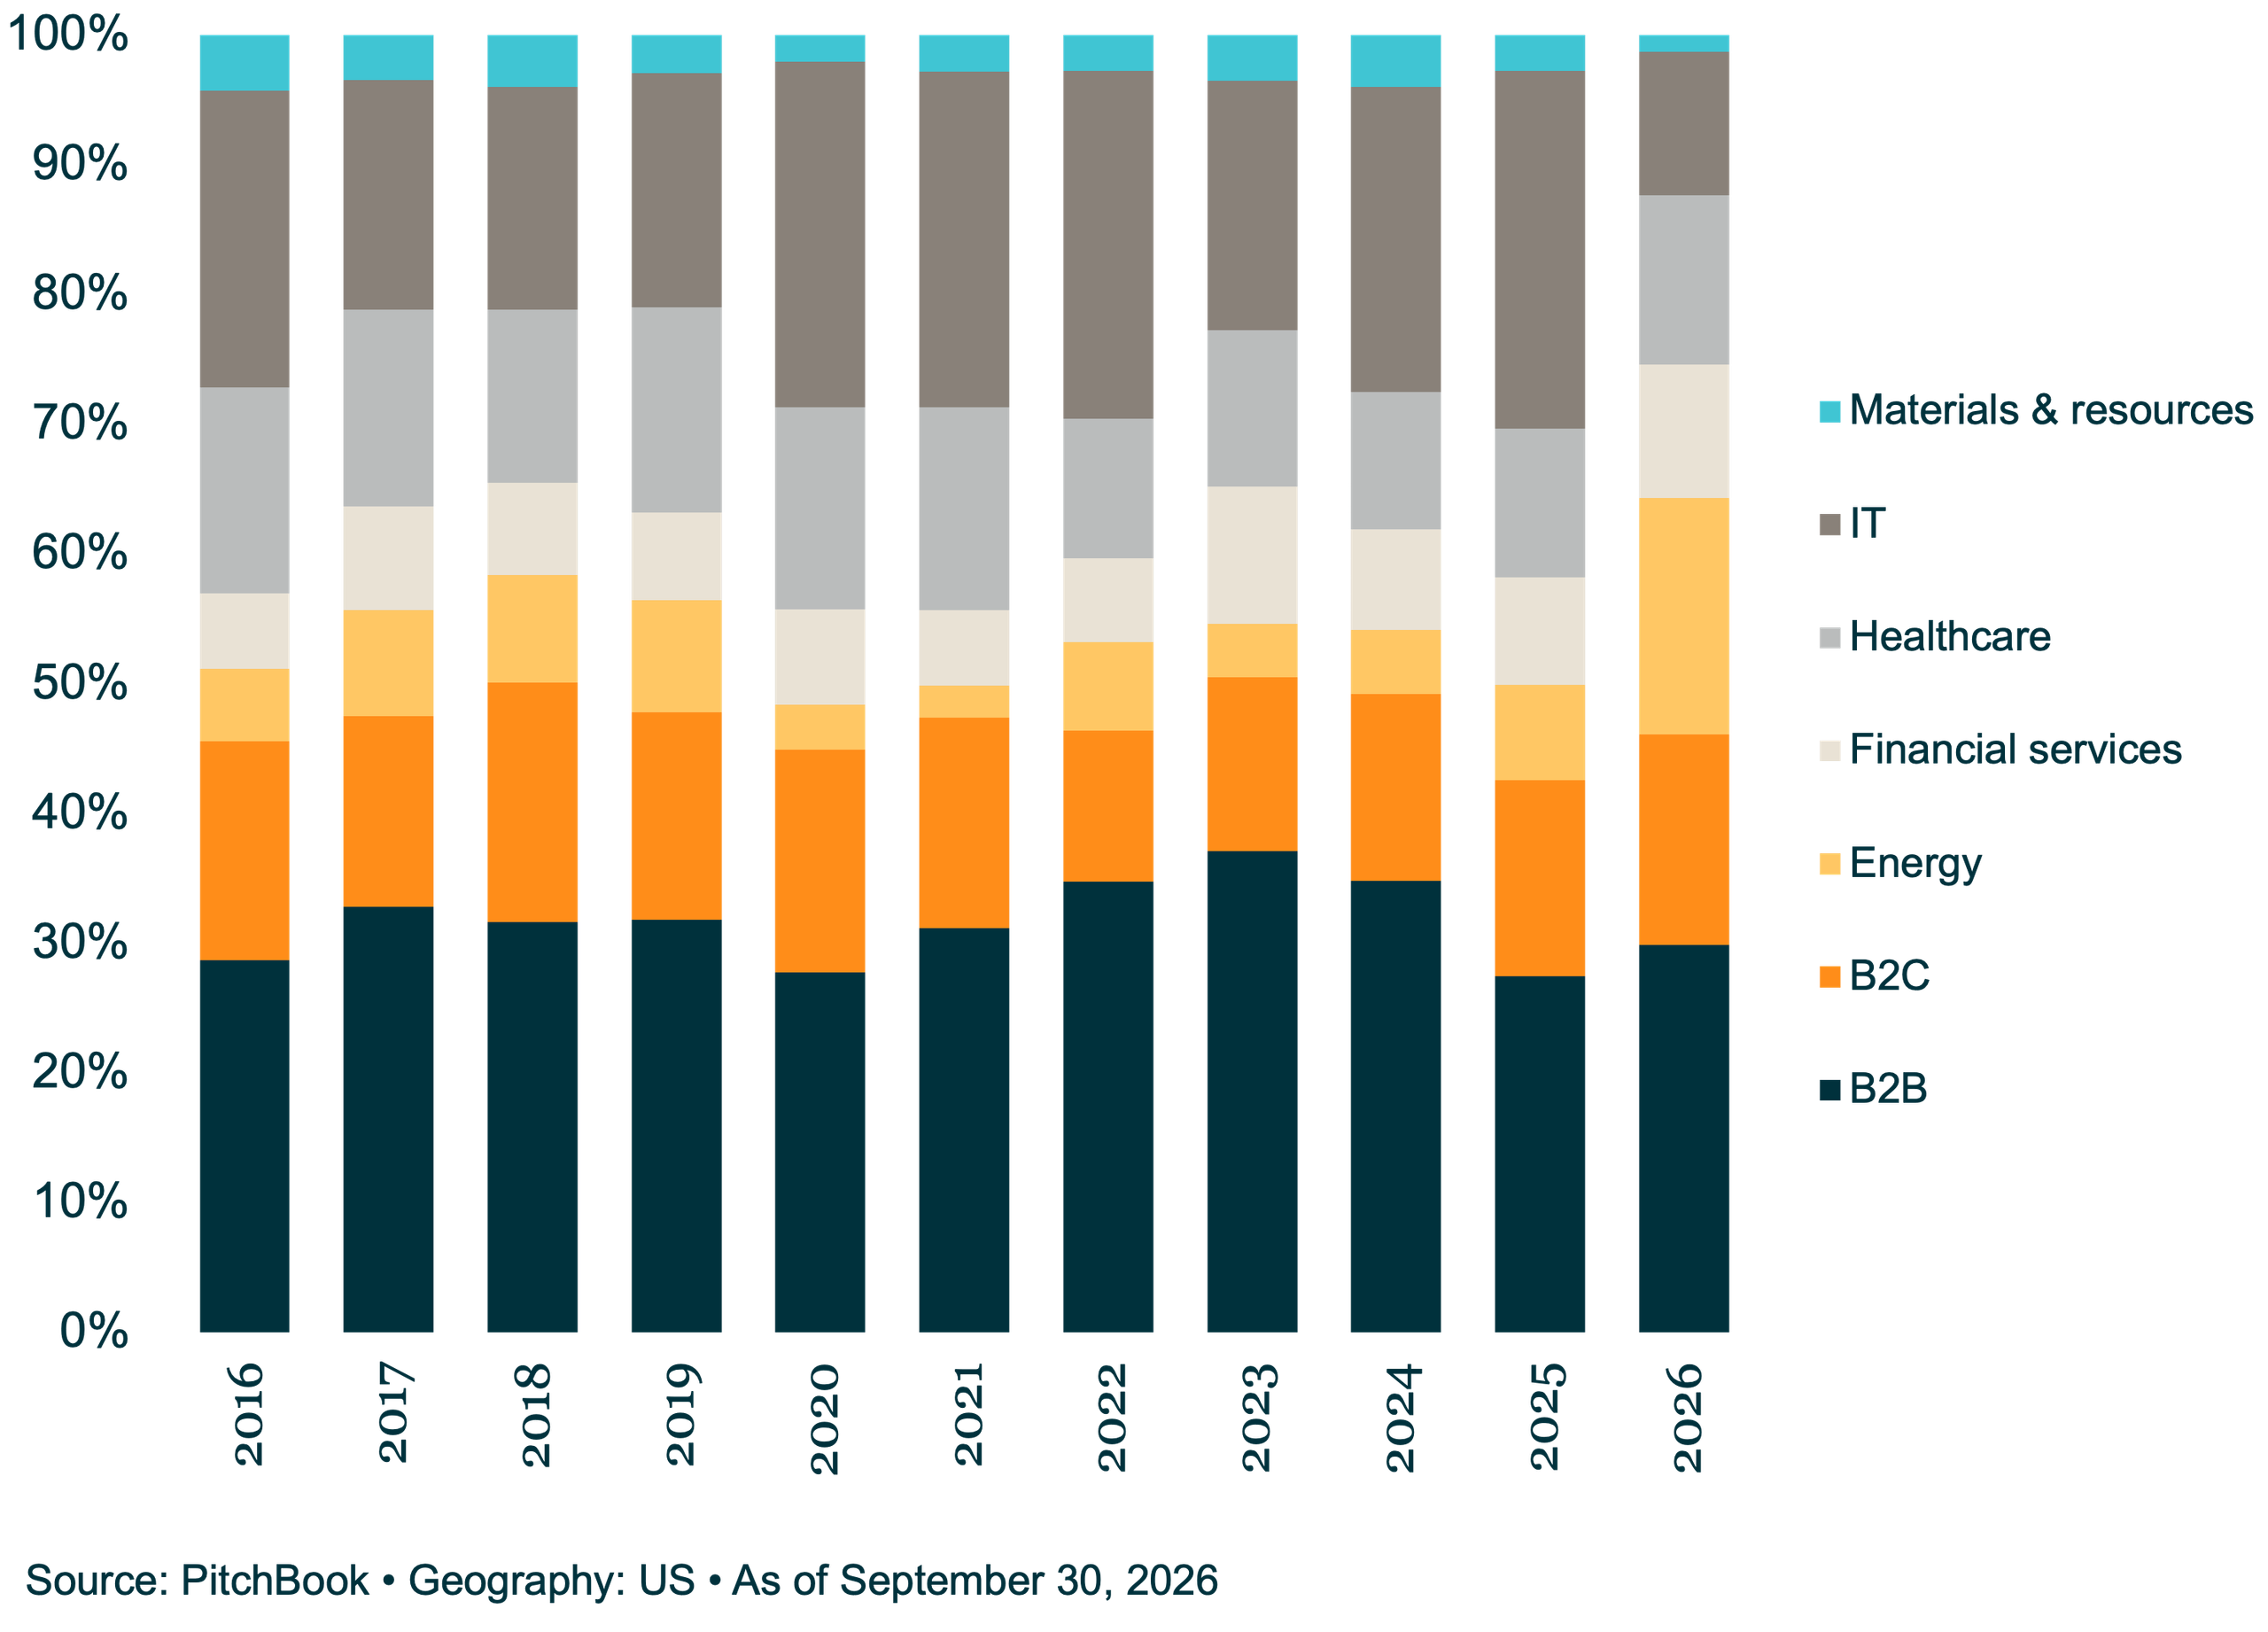
Sector rotation in capital deployment remains underway for the asset class. Because broader shocks in the asset class forced many sponsors downmarket, deal counts held up across sectors in Q2. Several sectors, including IT, saw increases in Q3, even as deal value told a different story. For example, deployment in IT in 2026 pales in comparison to activity in 2025 and has declined sequentially throughout the year, though the decline from $8 billion in Q2 to $7 billion in Q3 is much less severe than the near halving from $13.3 billion deployed in Q1 to $8 billion in Q2. The AI-related displacement fears driving the SaaS-pocalypse have kept many sponsors away from the sector, and that will likely continue through the remainder of 2026. Conversely, financial services has seen increasing activity throughout the year on a deal value basis, with 71 deals worth an aggregate of $10.7 billion transpiring in Q3 alone, while deal count has remained flat. Sector mix, more than overall activity, is where the market is being reshaped this year.
Latest news
Direct lending M&A declines QoQ and YoY except in upper middle market
M&A activity declined 12% in the third quarter of 2026 to 296 deals, from 336 recorded in the second quarter.