



Median Hold Period for U.S. Middle Market Companies Drops for First Time in Years
Private equity’s ‘hangover’ from the buyout boom era, with steadily aging investments skewing median holding periods for portfolios ever upwards, has been well-documented. PE holdings in the U.S. middle market—which has become increasingly popular among PE investors, its proportion of all U.S. buyout activity hitting close to 72% last year—is no exception, with the median hold time of a U.S. middle-market company jumping by 1.3 years between 2010 and 2014. But as quarterly data has rolled in throughout the year, for the first time in years, the median holding time has dropped, even if only by six months through the end of Q3. First and foremost, this shows just how successful PE sellers have been in exiting their holdings over the past couple years. The M&A boom is largely to thank for that, with secondary buyouts a well-utilized if still distant second exit ramp as well.
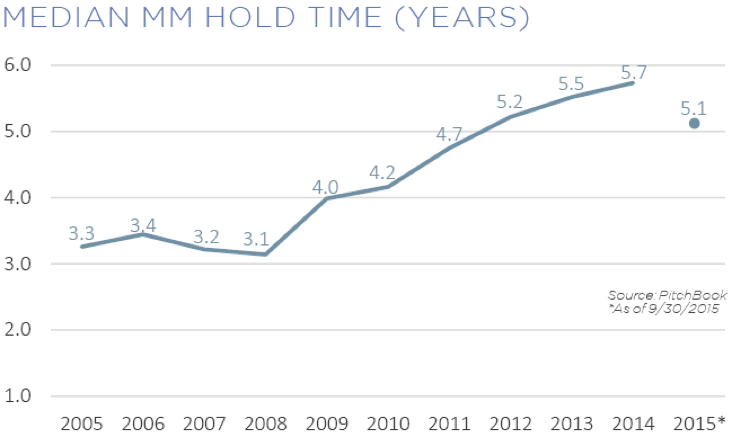
The potentially disquieting number, however, is that six months. Even in a heightened sellers’ market, the median hold time has only dropped to 5.1 years, which is still a considerable length of time. If M&A and sponsor-to-sponsor transactions continue apace, given the trend for acquisitive growth nowadays—not to mention the dry powder and cash & equivalents PE firms and corporate buyers respectively have on hand—many PE firms could still realize some of these aging investments. Selling off middle-market holdings in particular may prove easier than, say, selling companies valued at over $1 billion, but at this point, the quality of the companies that have been held for over five years must also be a consideration. Granted, some companies have taken a long time to recover from the Great Recession, but for those still being nursed back to health, exit prospects in the short-term are dim, and the long-term isn’t that long anymore when it comes to typical PE fund lifetimes. It really comes down to just how hungry corporate buyers will be for top-line expansion, as secondary buyouts aren’t likely to become a significant enough source of liquidity.



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.