



Download PitchBook’s Report here.
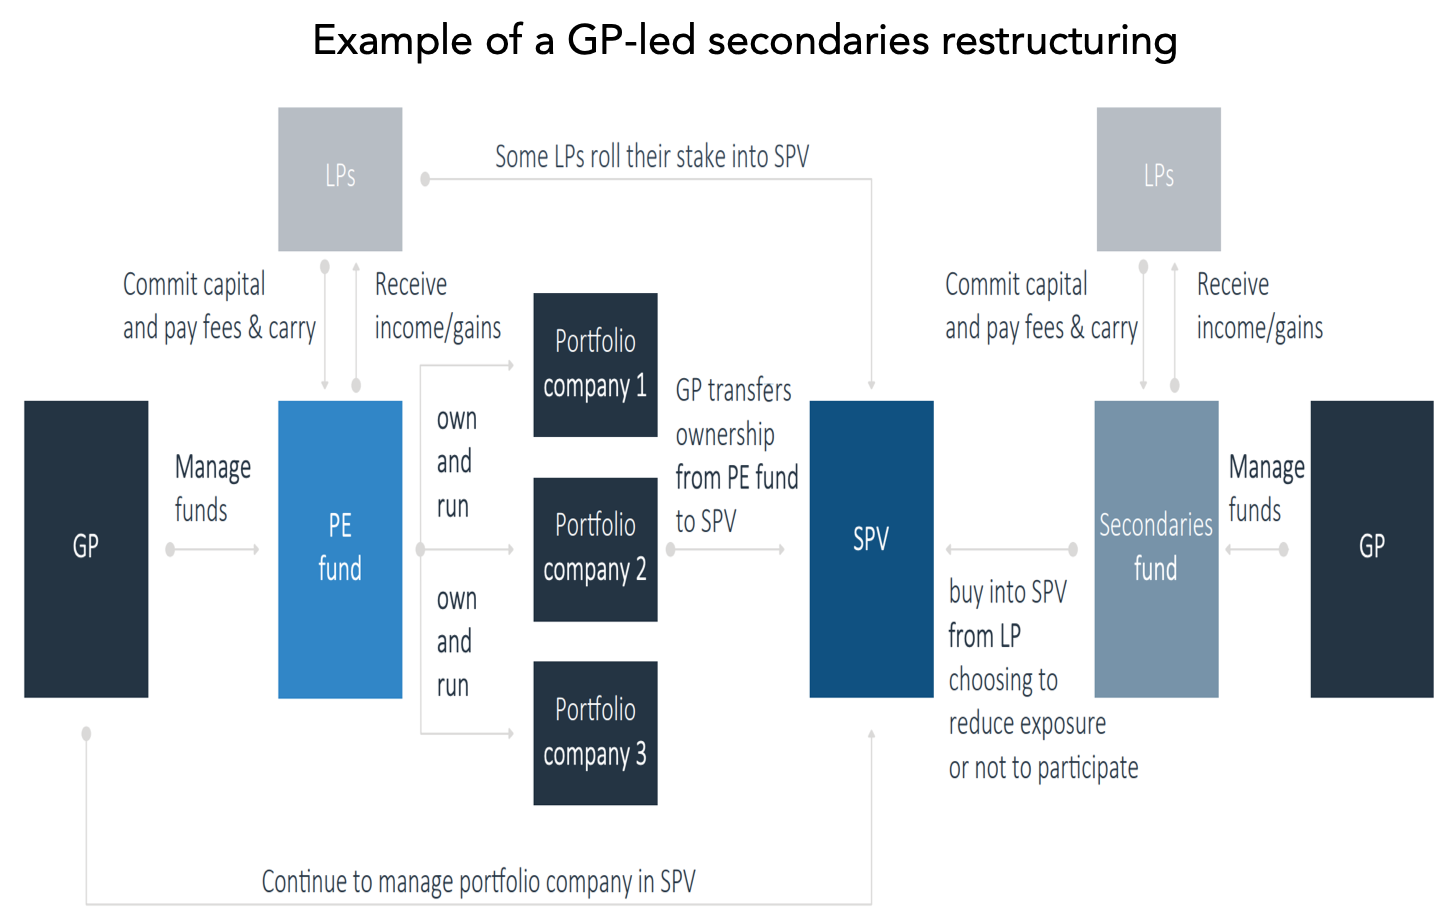
Last week we highlighted our new analyst note on extended holding periods. Now available, the note dives into the pros and cons of GP-led secondaries, which have steadily become more popular. The market has become the industry standard for handling successful assets that can’t be held any longer in their original funds. Transactions range from simple single-asset deals to more complicated, multi-asset restructurings.
A good example happened in 2018 with Kronos, an HR software provider. Hellman & Friedman and JMI had owned the company since 2007. Eleven years into its holding period, the H&F fund was nearing the end of its life and exploring options for Kronos, which still had upside. H&F opted for a single-asset restructuring, which allowed the fund’s LPs to roll their stakes over or cash out entirely. Rather than bring in outside investors, H&F allowed liquidating LPs to sell their stakes to the fund’s other LPs, or to H&F itself. The plan paid off—last month H&F merged Kronos with Ultimate Software, a separate portfolio company with an $11 billion purchase price; the combined brand was valued at $22 billion. The 2007 Kronos buyout was for $1.8 billion, and while we don’t know what the ultimate ROI looks like, we can assume it’s looking good. The extended hold, and LPs’ willingness to wait out a bit longer, likely paid dividends for everyone involved.
The LPs were nice to do that, but the restructuring had to make sense for them. In the case of Kronos, they knew H&F had a winner on its hands and had good reason to hold onto it. That translated to relatively low investment risk as opposed to committing the same money to an unknown fund—comfort as compensation, in this case. On the other hand, not all deals turn out to be Kronos deals. LPs have to think fast—a 20-day turnaround is best practice according to the ILPA, which isn’t a lot of time to digest 1,000+ pages of documents and do thorough due diligence. Trust might be an unspoken factor. Drew Brees is getting re-signed and the Chargers are moving on from Philip Rivers, and the fine print didn’t play a role in either case. QBs aren’t portfolio companies, but winning investments are winning investments.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…