


Download Report click here.
Healthcare-related PE activity broke records last year. Both counts and value reached new highs in 2017, according to RSM’s Q1 Healthcare and Life Sciences Report, done in conjunction with PitchBook. In all, 692 transactions were done totaling $86.1 billion in North America. Two concurrent trends joined forces—a number of highly valued deals were made that boosted total value, while a surge in add-ons helped pushed volume just past 2016 levels. Private equity continues to invest in the sector with care, overlooking to some degree the amount of regulatory uncertainty swirling around the industry.
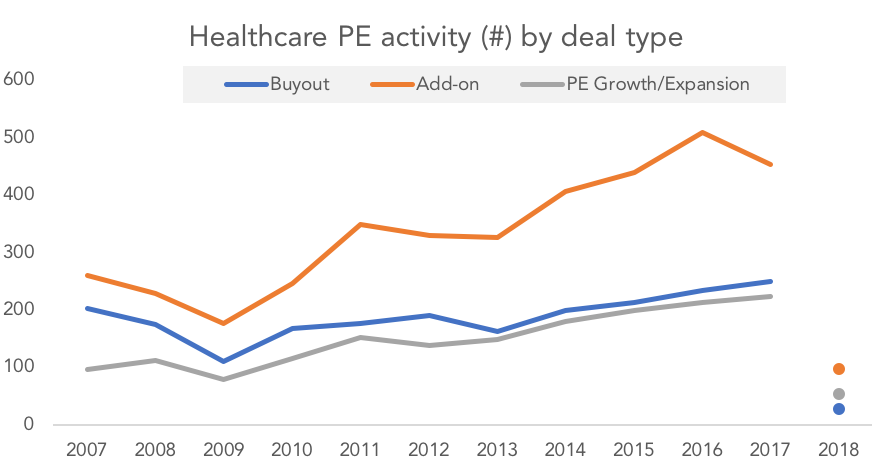
The largest opportunity remains the consolidation play. The buy-and-build model is perfectly suited to healthcare at the moment, especially as providers are trying to keep pace with consumer demands for cheaper, non-hospital-based services. Moreover, the industry is gravitating toward consolidation as a way to reduce back-office costs and bring several smaller regional providers into larger, more centralized, more cost-effective platforms. The accompanying chart gives a sense of just how prevalent add-ons have become. Starting in 2011, add-ons became much more frequent compared to platform buyouts; for the first time that year, add-ons nearly doubled the number of buyouts by count in a single period. The trend gained steam from there, culminating in 2016 when add-ons outpaced platforms 509 to 234. While 2017 hit a speedbump in add-on volume, there’s no evidence to suggest that the buy-and-build trend has peaked. The number of subsectors within healthcare that will continue benefitting from consolidation is large, and PE’s opportunity to capitalize on this trend—in the biggest and arguably most fragmented healthcare market in the world—is only beginning.
Contact: Alex Lykken
alex.lykken@pitchbook.com




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…