


Download PitchBook’s Report here.
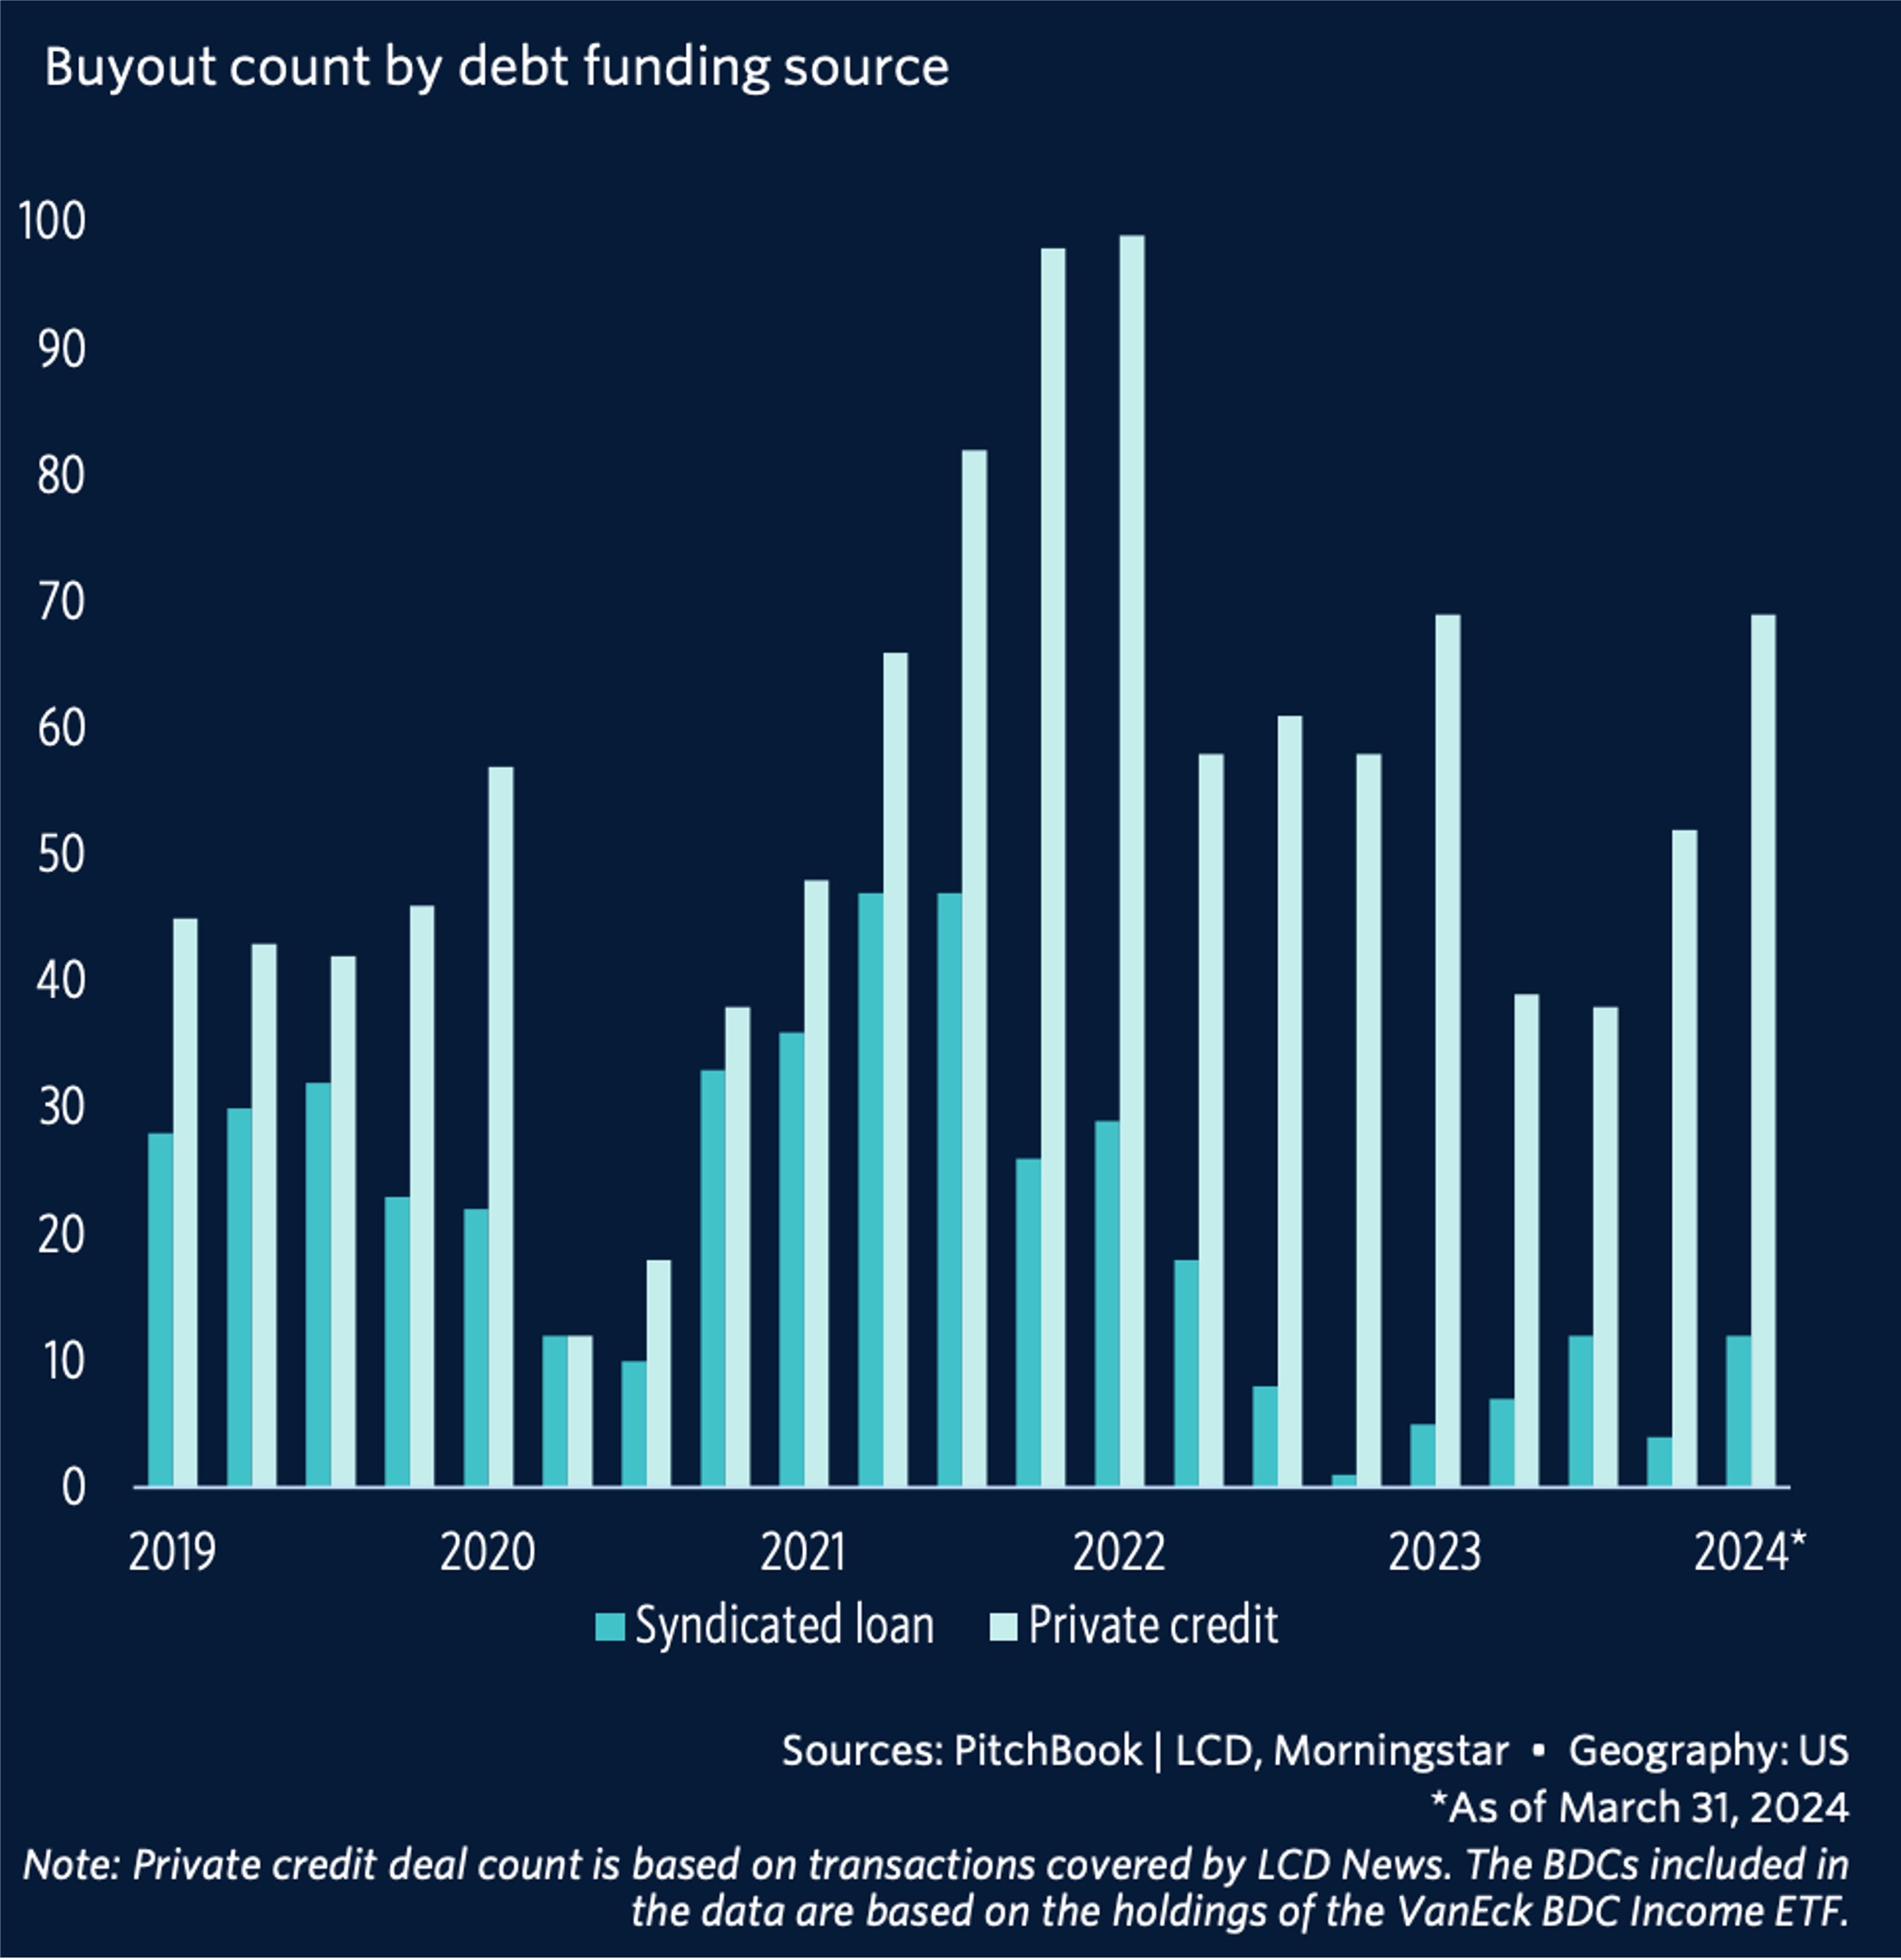
Private credit continues to dominate the number of buyout financings while lending from public business development companies (BDCs) suggests direct lending may have bottomed in H2 2023, but competition is increasing, leading to private lenders having to lower their prices to secure deals. It is possible buyout activity may begin ticking up more, but leverage constraints may be the key inhibiting factor that continues to exert a dampening effect and shan’t subside until monetary policy changes.
(Past performance is no guarantee of future results.)




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…