


Download PitchBook’s Report here.
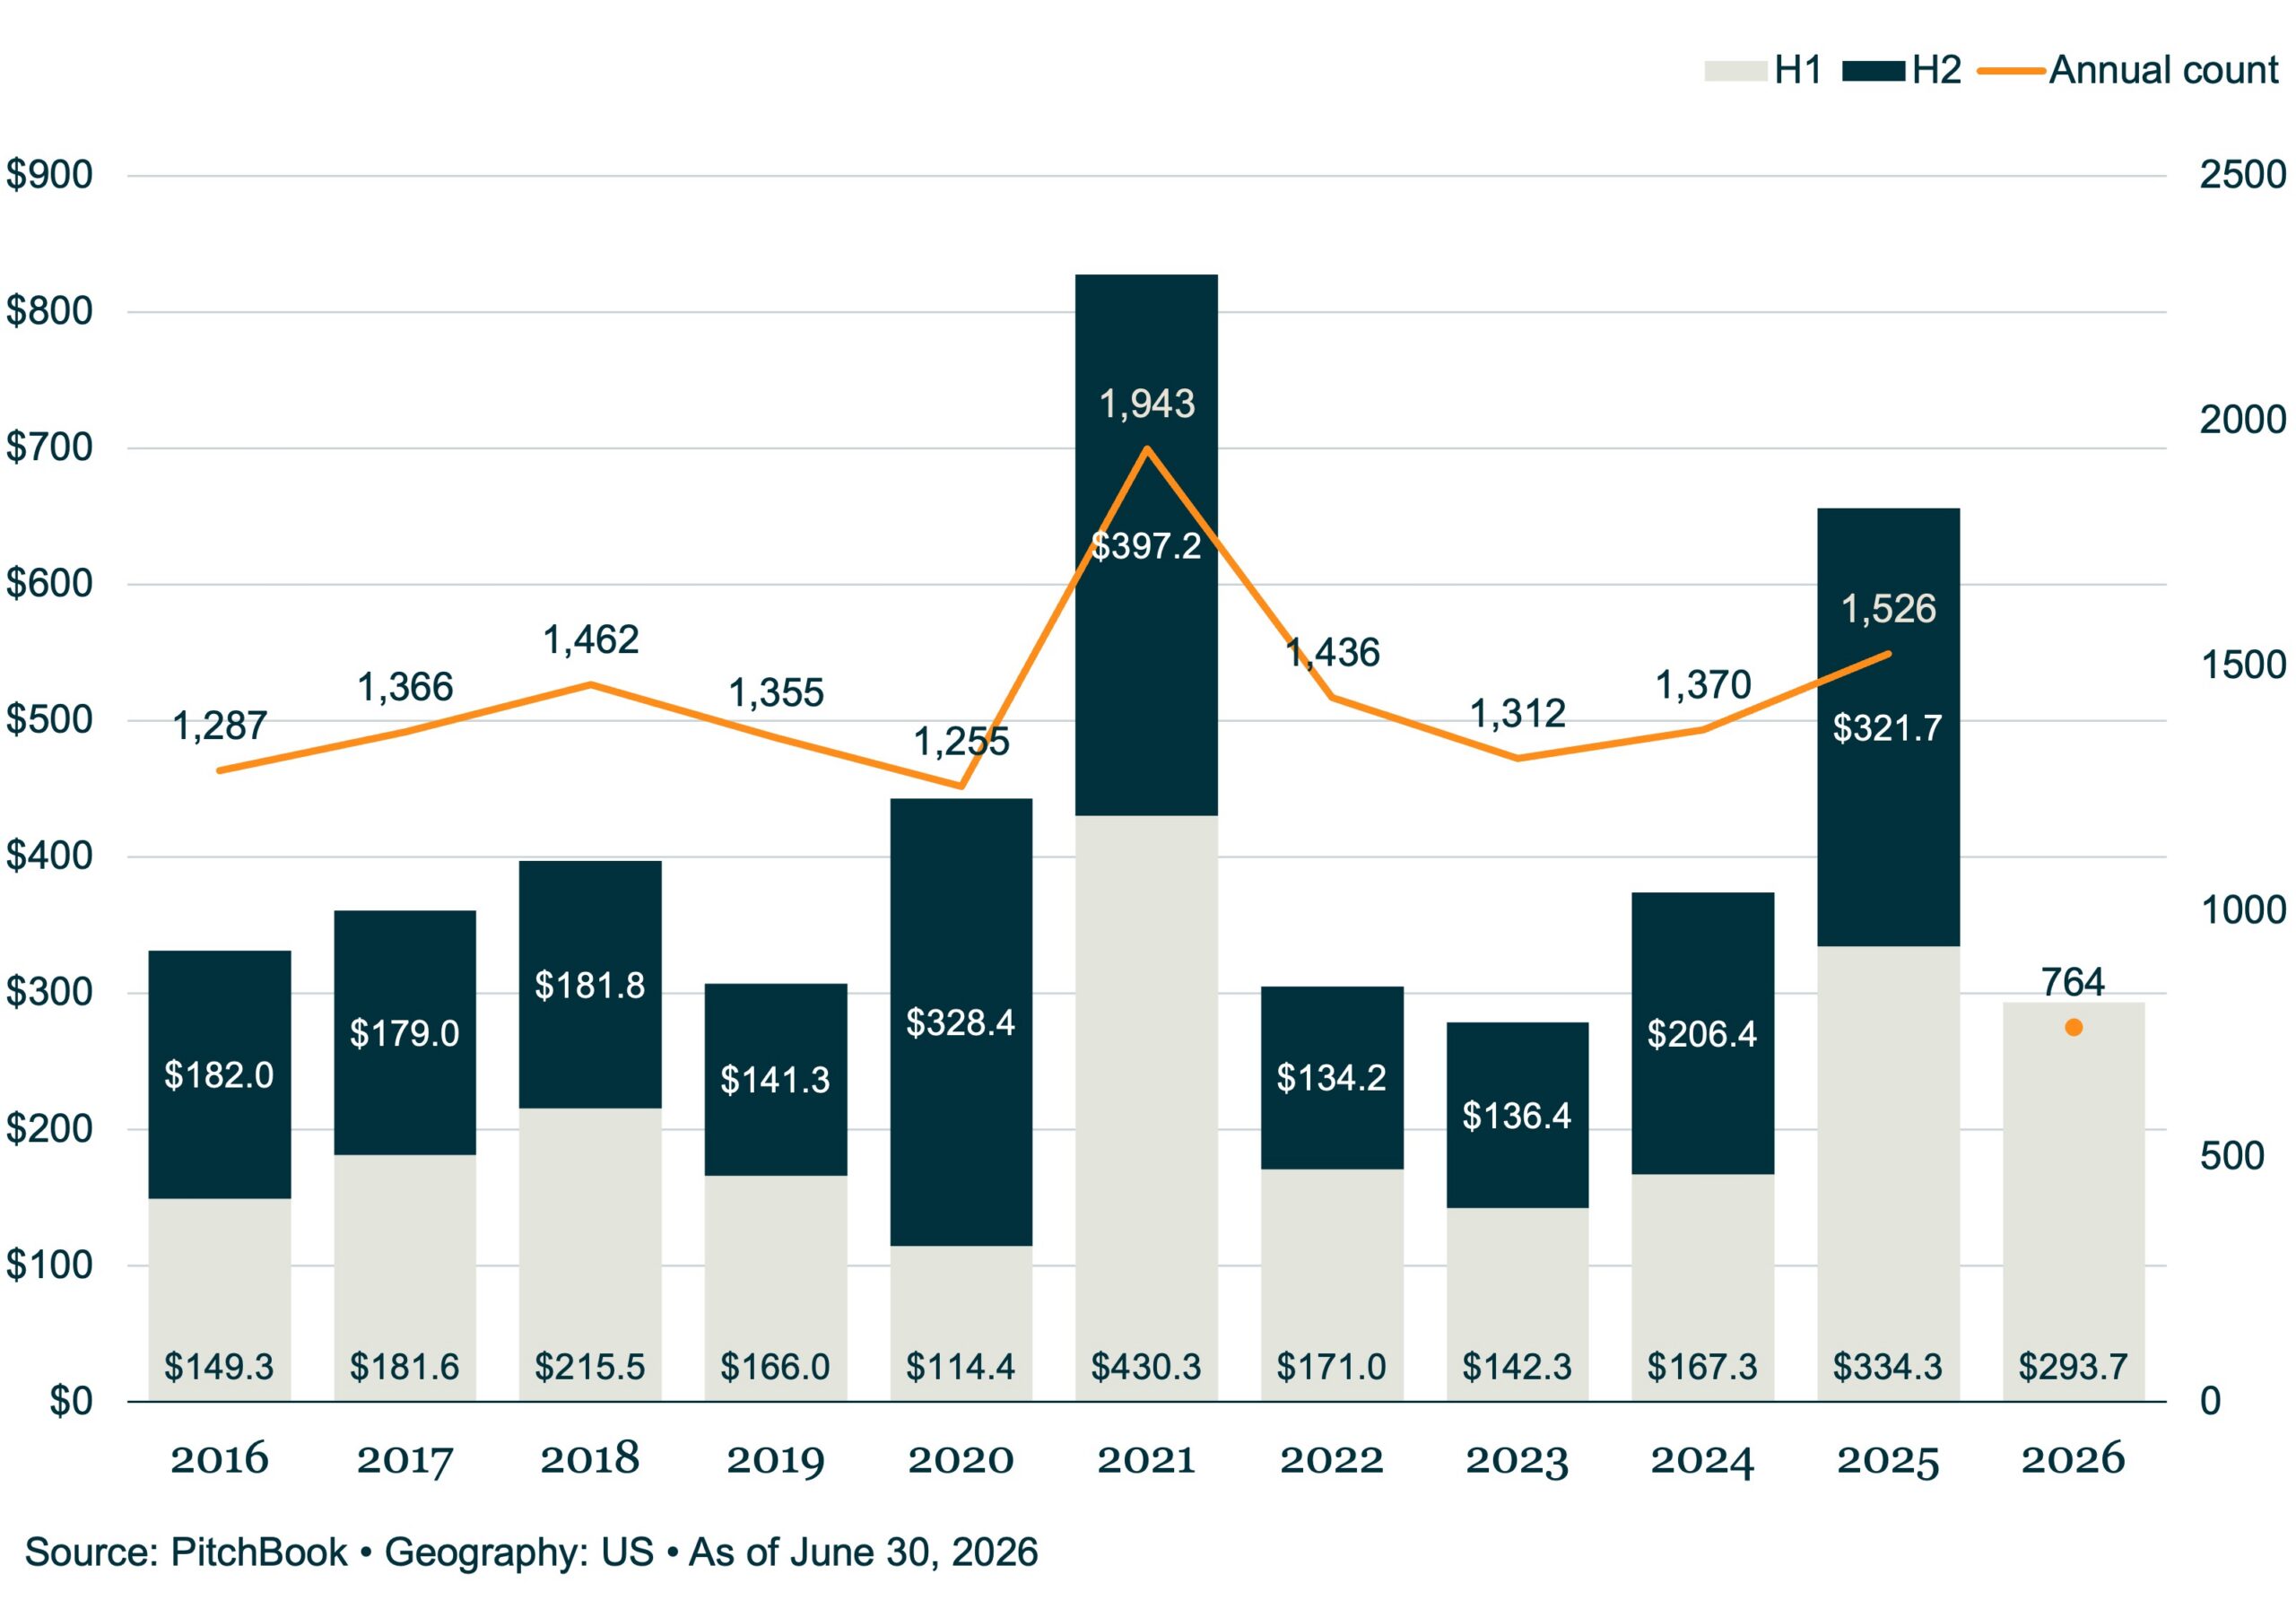
Exit value fell to $102.6 billion in the second quarter—down 46.3% from the prior quarter and 7.4% YoY—while exit count dropped to 353, a 14.1% quarterly decline and a 5.4% rise against Q2 2025. The figures include estimates for latereporting transactions. The same macro forces depressing dealmaking, such as costlier financing, an uncertain rate path, and software repricing, are at work here, with the added drag of an already constrained exit landscape. On a YTD basis, the contraction is shallower than the quarterly figures imply, with the H1 2026 exit value of $293.7 billion down roughly 12% against the comparable 2025 window. This is a reminder that a stronger first quarter cushioned an otherwise difficult first half of the year. Q2 exit activity is comparable to the dip in 2025, and exit value sits above pre-pandemic averages, but realizations remain stubbornly dependent on a small number of large transactions to generate aggregate value. Mega-exits, those of $1 billion or more, totaled $63.2 billion across 23 transactions, anchoring more than 61% of the total exit value in Q2. This demonstrates that premium assets can still clear at scale, but it underscores how little of the broader portfolio backlog is finding a path to liquidity.


Latest news
US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
