


Every big theatrical release eventually makes its way to streaming. It gives people who missed it in theaters a chance to catch up. And for those who already saw it, a second look at the details they missed the first time. The Lead Presents: Making Sense of Private Credit Defaults had its own debut the other week, drawing more than 700 registrants for a conversation with all four major rating agencies on how they calculate and measure defaults. With the replay now live, we wanted to walk through a recap of our conversation. Here are the key scenes worth revisiting.
The session picked up right where Different Numbers, Different Stories left off. The reason default rates range so widely is that everyone’s measuring something slightly different. One firm may focus on missed payments. Another might include distressed exchanges like maturity extensions and PIK amendments. The universe itself can differ in composition, whether in size, how it’s weighted (by issuer or by volume), or whether it includes loans further down the capital stack rather than those most senior. As one panelist framed it, these differences don’t mean one rate is more right than another. They each serve a purpose, because it’s a non-homogeneous market.
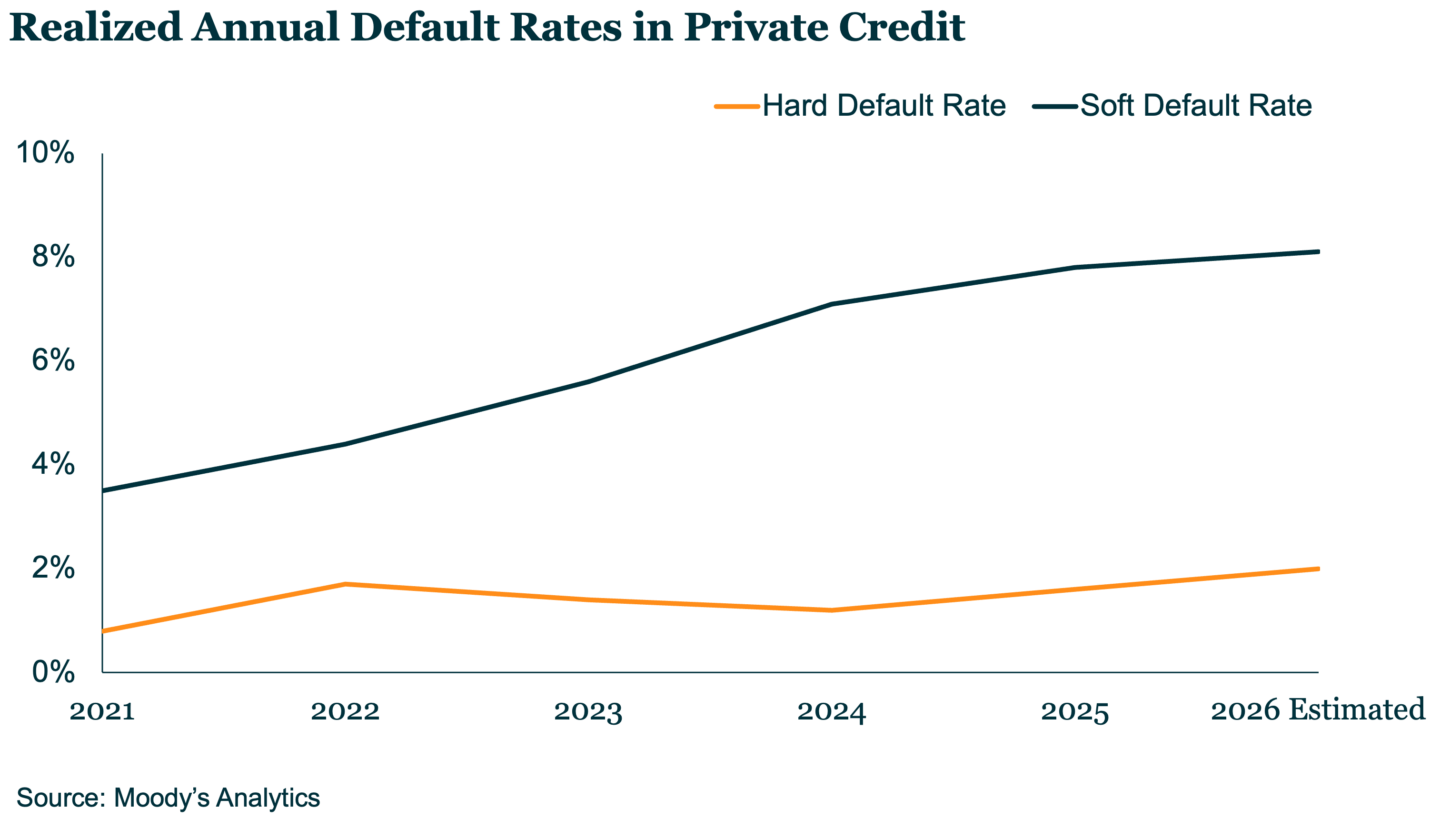
The bigger theme, though, was the growing gap between “hard” and “soft” defaults. Soft credit events, which include maturity extensions, PIK amendments, and covenant breaches, make up the so-called “shadow rate.” According to Moody’s, these soft credit events have risen from roughly 3.5% to nearly 8% since 2021 (see Chart). Hard defaults, meanwhile, missed payments and bankruptcies, have stayed in a range of 1-2% over that same stretch. That’s consistent with a point we’ve made throughout this series. Middle market direct lenders have a number of tools to get back to the table early, before those problems turn into a real loss.
Software, everyone’s favorite topic this year, came up too. The takeaway is that AI’s impact on the sector is more nuanced than an “AI is coming for credit” headline would suggest. Fundamentals still look strong by most measures, with healthy growth rates and low defaults. But a few panelists flagged that risk is concentrated in specific business models, with application-layer software facing more pressure than the sector overall. With a meaningful maturity wall still ahead, panelists noted they’re watching closely to see how that plays out.
Finally, we walked through recoveries. Like software, the story is nuanced. Recovery rates have moved lower and are converging to levels in the broadly syndicated and high yield markets. But similar to what we covered in Scrambling for Par, tighter middle market documentation is still providing a real cushion, particularly for smaller companies. S&P found recoveries on smaller middle market loans running near 84 cents on the dollar, well above the 68 cents typical for larger deals.
Consider the credits rolled. But like any rewatch, it’s easier to connect the smaller details. Since the beginning of September, we’ve been trying to convey two things: a default rate depends on how it’s measured, and what you actually lose depends on the recovery that follows.
For those who missed it live, enjoy the replay. Popcorn optional.


Why Capital Solutions: The Walking Debt
The word “zombie” traces to Haitian folklore and entered the English language in the early 1800s.